The idea

Buy long-dated calls on my watchlist names that are trending up.

This is the strategy behind my real-money Public Portfolio Challenge. Before each test, Aurora tried four position sizes on the dates before it and kept one.

Describe a trading idea. Get a bot tested on data it never saw.

Write it the way you would say it. Aurora, the research agent, turns it into rules and backtests them after fees. Then it tests them on later dates.

36,148 people have run 652,784 backtests on NexusTrade. I also trade it with $25,000 of my own money, in public.

Where would you like to start?Let’s build your first plan.
Studied before the first test
Sep 2020 – Aug 2024
Three tests on dates the rules never saw
Aug 2024 – Sep 2026
My strategy +501.2% SPY +38.8%

Each 252-day test started with a fresh $25,000, and the line chains the three of them. The strategy beat SPY in all three windows it had never seen. Watch the rules change or open the study.

Then the line moves forward, and the rules change with it.

Before each 252-day window, Aurora tested four position sizes on the dates before it and kept the one with the best Sortino ratio. That version then ran on dates it had never seen.

  1. Aug 17, 2024 – Apr 25, 2025Window one: 10% of the portfolio in each position.Picked on dates through Aug 16, 2024, where its validation return was +121.8%. On the unseen dates it made +38.6% while SPY lost 0.7%, after falling as much as 31.1%.
  2. Apr 26, 2025 – Jan 2, 2026Window two cut each position to 5%.It made +144.0% against SPY’s +25.1%.
  3. Jan 3 – Sep 11, 2026Window three cut each position to 3%.It made +77.8% against SPY’s +11.7%, and its largest fall shrank to 10.7%.
  4. All threeChaining the three $25,000 tests gives +501.2%. SPY gives +38.8%.The strategy beat SPY in every window it had never seen. Open the study.

Chosen for window one

Each position
3%5%7%10%

Chosen Changed since the last window

The full record of all three windows

Each window’s settings came from the dates before it. The test result never fed back into the choice.

Public Portfolio Challenge walk-forward optimization, three windows
WindowTest datesChosen settingsValidation returnTest returnSPYClosed tradesFeesLargest fall
1Aug 17, 2024 – Apr 25, 202510% per position+121.8%+38.6%−0.7%282$239.34−31.1%
2Apr 26, 2025 – Jan 2, 20265% per position+248.6%+144.0%+25.1%349$244.14−13.6%
3Jan 3 – Sep 11, 20263% per position+306.2%+77.8%+11.7%283$123.93−10.7%

Fresh $25,000 per window, fees of 0.1% of each stock trade and $0.65 per option contract, a 14-day embargo before each validation period, and the highest validation Sortino ratio picked among versions that traded at least nine names. The setting searched is the share of the portfolio in each position. These are historical simulations. The live account below runs the current version of the same strategy. Open the study.

Never traded? Start with the basics.

Algorithmic Trading Fundamentals

Level
Beginner
Length
6–8 hours
Rating
4.9 from 14 reviews
Code
None needed
Hour 0, introductory modules freeAbout 6–8 hours
  1. See how the pieces fitIndicators, conditions, strategies and portfolio backtests.
  2. Build your first indicatorsA 10-day SMA and an RSI, through Aurora.
  3. Write conditionsSMA-to-price and RSI thresholds inside SPY strategies.
  4. Make a first strategyA paper portfolio and an AMZN buy rule.
  5. Backtest it against SPYCompare your strategy with buy-and-hold.
  6. Check before you deployPaper deployment and the checks before going live.

Past the last test, you decide what runs.

Paper trade it

It needs no brokerage account.

Take it live

  • Alpaca
  • Public
  • TradeStation
  • Tradier
  • Robinhood

Automation runs only after you approve it and switch it on.

Build on it

pip install nexustrade
npm install nexustrade

You can also connect the MCP server or the REST API. Read the developer docs.

The line ends today, with my own money.

I’m Austin, the founder. I started this portfolio with $25,000 of my own money on May 5, and every position and fill is public.

So far I’m 6.2 points ahead of SPY.

Portfolio value, Oct 21
$28,246.82
Since May 5
+13.0%
SPY total return
+6.8%
My portfolio SPY, dividends reinvested

Or start from a strategy someone already tested

Fork one and test it yourself. Browse every template.

Open-source strategy templates and their public records
TemplateLast 12 months1-year returnLargest fallSortinoAccess
Venezuela Equal WeightBy Austin · Forward test · paper+53.7%−15.5%3.08Free to fork
SPXL Scaling into Drawdowns V5 (Shorter Cooldown)By Austin · Forward test · paper+52.9%−12.5%2.31Free to fork
Drawdown-Based AccumulationBy Austin · Forward test · paper+39.7%−32.8%1.32$39.99 a month

Each record is labeled paper or live. Updated Oct 21, 2026. Past performance does not guarantee future results.

You did an excellent job of considering all aspects of trading and research which made the application smartly transition from research to strategy, to watchlist, to trade… very nicely done.
Spencer K. Chief Finance Officer / Institutional Investor
  • I discovered NexusTrade on YouTube and was so impressed that I invited the founder to speak at my MBA class.

    Michael P. Senior Lecturer, Harvard Business School

  • There are not a lot of people (particularly in retail) building what he’s building, and the platform is incredible.

    Trevor R. Managing Director at a quant firm

  • Even though I know how to code, it’s still very enjoyable to be able to do this with such ease. I was able to optimize my strategy to the fullest.

    Delanoe P. Artificial intelligence engineer

Questions people ask first

Are the results here real money or simulations?

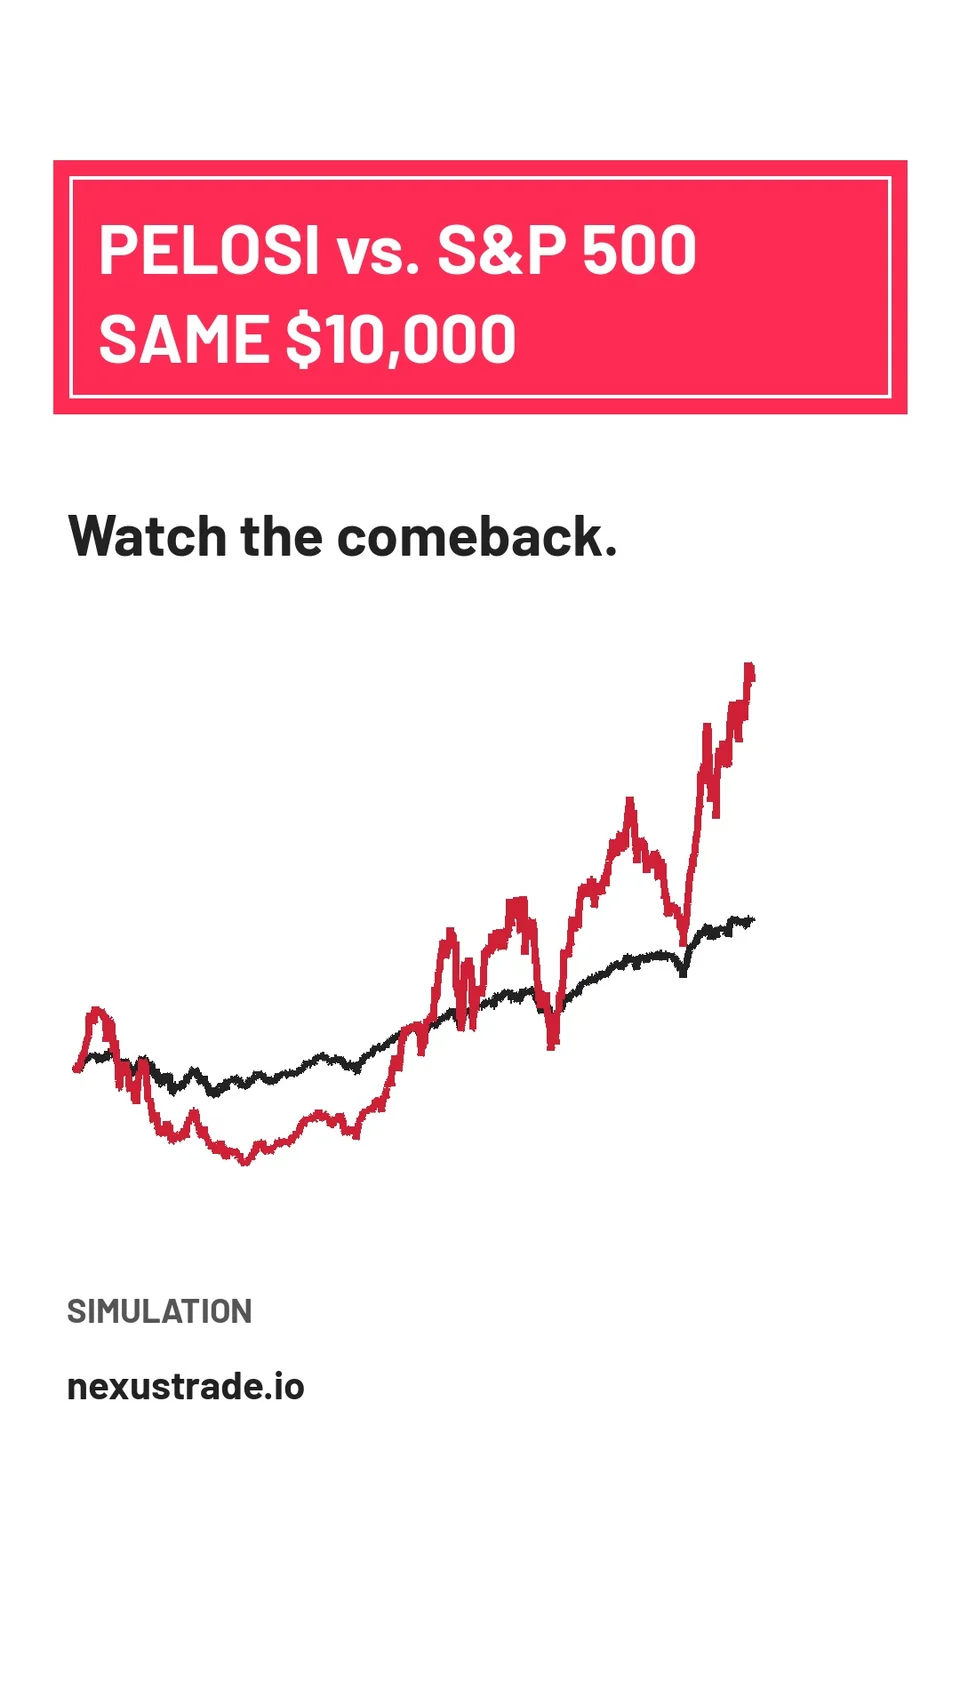
The founder’s Public Portfolio Challenge uses real capital. Template records are labeled paper or live. The Pelosi backtest and the walk-forward study are historical simulations. In the walk-forward study, each window’s settings were picked using only earlier data, and every date had already passed when the study ran. Open each record to inspect its rules, dates, fees and risks.

Do I need to code or already have a strategy?

No. The three-question start asks about your experience, priorities and interests, then suggests ideas to test. Choose one or bring your own. Aurora works in plain English, and you can also build rules by hand.

Can I trade real money with NexusTrade?

Yes, if you choose to. Paper trading needs no brokerage. Live trading connects to Alpaca, Public, TradeStation, Tradier or Robinhood, and stocks, options and crypto are supported. Your brokerage decides which of those you can trade. Automated live trading requires approval, current consent and automation you switch on yourself.

What is free, and when do I pay?

You can fork strategy templates and build strategies by hand for free, with two paper portfolios of up to ten strategies each. Aurora research uses tokens. Paid plans include a daily allowance, and you can also buy tokens without changing plans. How the allowance works.

Why does an annual plan show a monthly price?

The monthly figure is the annual charge divided by twelve, so you can compare plans. The Data-Driven Investor plan charges $480 once a year, which shows as $40 a month. You can also pay $49.99 monthly or $13.99 weekly.

Does a paid platform plan include every template?

Some strategy templates are free to fork, and others have their own subscription price. A platform plan covers its research allowance and platform limits. A paid template subscription covers that one template and leaves your platform plan as it is.

Bring the idea you keep coming back to.

Observer
Free
Fork templates, build strategies by hand and keep two paper portfolios of up to ten strategies each.
With Aurora research
From $40 a month
Billed annually at $480, with a 30-day money-back guarantee on platform fees.