I used OpenAI’s rumored GPT 5 to create a trading strategy. Financial advisors should be in full-blown panic mode.
“It returned 30% in one year. The broader market returned 2.”

 Published in
DataDrivenInvestor
11 min read
In April 2025, I was trying to work out who was behind Quasar and what its API could do.
It started a few days ago when OpenRouter announced their first “stealth” model. This model had a name as celestial as the performance it delivered: Quasar Alpha.
The reported OpenRouter token ranking drew my attention, and I was impressed by the model in the April 2025 tasks shown here. That is my experience with those requests, rather than a survey of every user.
There are new stealth large language models coming out that’s better than anything I’ve ever seen.
Introducing “Optimus Alpha” and “Quaser Alpha”
medium.com
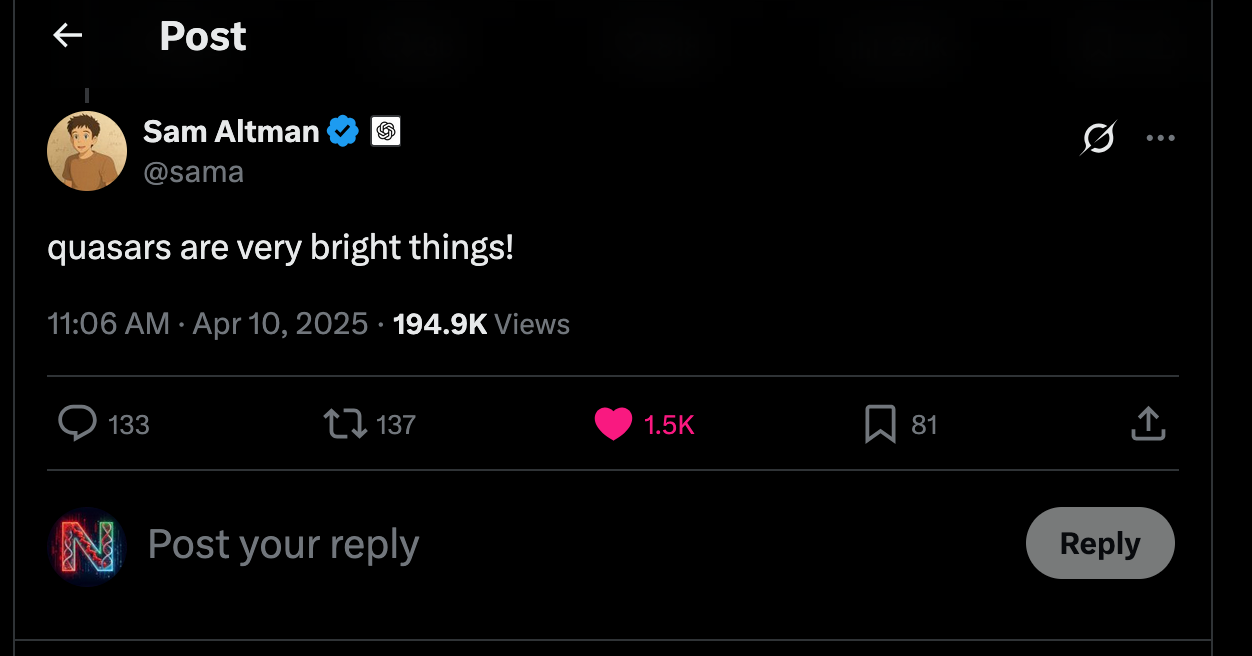
In April 2025, I interpreted Sam Altman’s quasar tweet as a hint about the hidden provider. That was speculation. The model identifier in the main experiment is Quasar Alpha; this article does not confirm that it was GPT-5 or GPT-4.5.
Knowing that Claude can create profitable algorithmic trading strategies, I was curious to see how well “Quasar” did too.
And just like Claude was able to beat the market, Quasar DESTROYED it. By an insanely ridiculous margin.
As someone who went to Carnegie Mellon University, one of the world’s best schools for artificial intelligence, on a full tuition scholarship, these results absolutely shocked me.
They’re gonna shock you too.
What is Quasar Alpha?
Quasar Alpha is a new “stealth” model provided by OpenRouter. A stealth model is essentially when an AI company wants to hide the identity of the model, but still release it to the public to further improve on it.
Being a “cloaked” model, the inputs and outputs are logged and sent back to the provider for further training.
And yet, despite not having a big name behind it like “OpenAI” or “Anthropic”, this stealth model quickly rose to #1 on OpenRouter. Based on people’s subjective (and sometimes objective) experience with it, it’s no doubt that this is one of the best models we’ve ever seen.
Additionally,
- On many benchmarks including NoLiMa (a long context information-retrieving benchmark), Quasar Alpha is litterally the best.
- Despite being extraordinarily effective, the API was offered free when I tried it in April 2025 (alongside its mysterious cousin Optimus Alpha)
- It has an extraordinarily large 1 million token context window
- And most importantly, in my objective complex reasoning task, Quasar Alpha achieved among the highest score among any of the other models tested by FAR
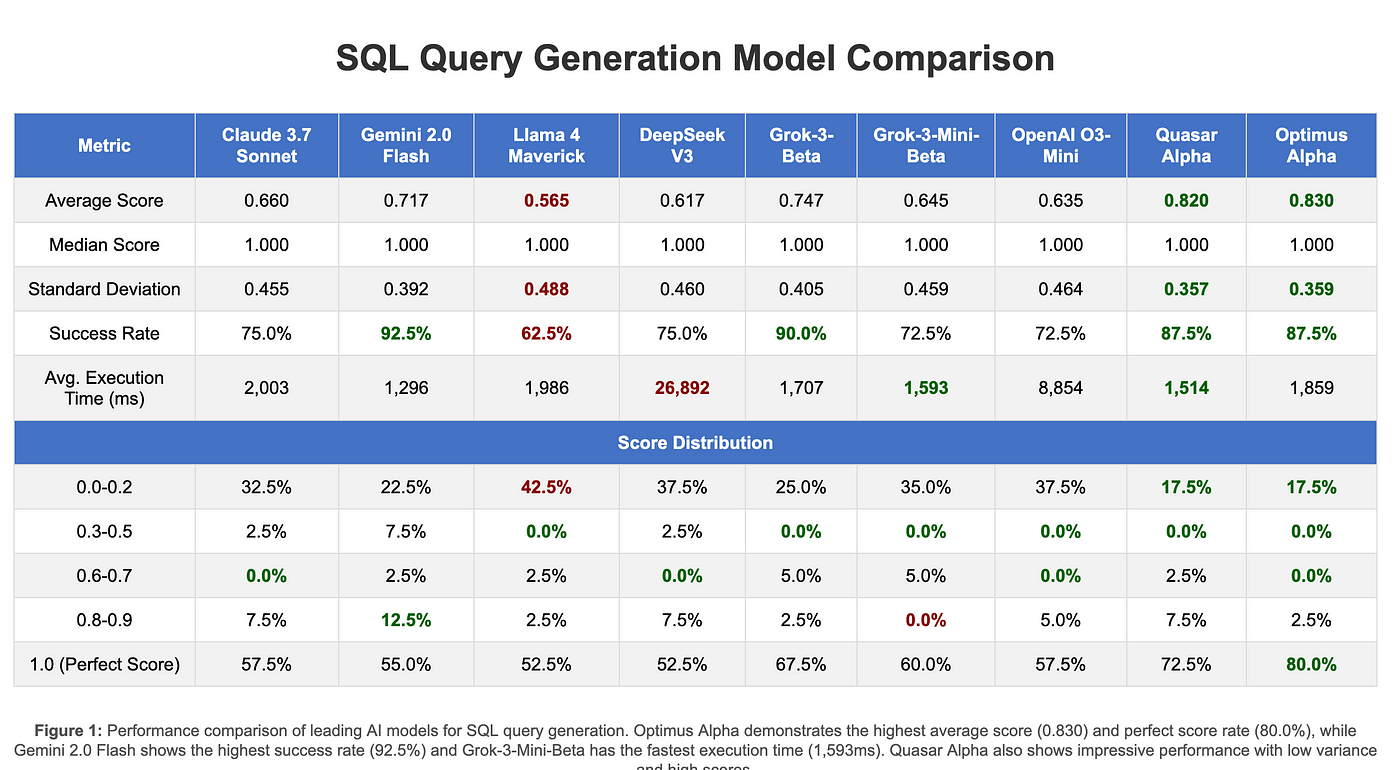
Thus, knowing that this model is amazing in literally every way, I wanted to see if it could create a better trading strategy than Claude 3.7 Sonnet.
It did not disappoint.
There are new stealth large language models coming out that’s better than anything I’ve ever seen.
Introducing “Optimus Alpha” and “Quaser Alpha”
medium.com
Recapping how I created a trading strategy with Claude 3.7 Sonnet?
In a previous article, I described how I used Anthropic’s Claude 3.7 Sonnet to create a market-beating trading strategy.
I told Claude 3.7 Sonnet to build me a mean reverting trading strategy. It’s DESTROYING the market.
The strategy that would’ve survived the Trump tariffs
medium.datadriveninvestor.com
To recap how I did this:
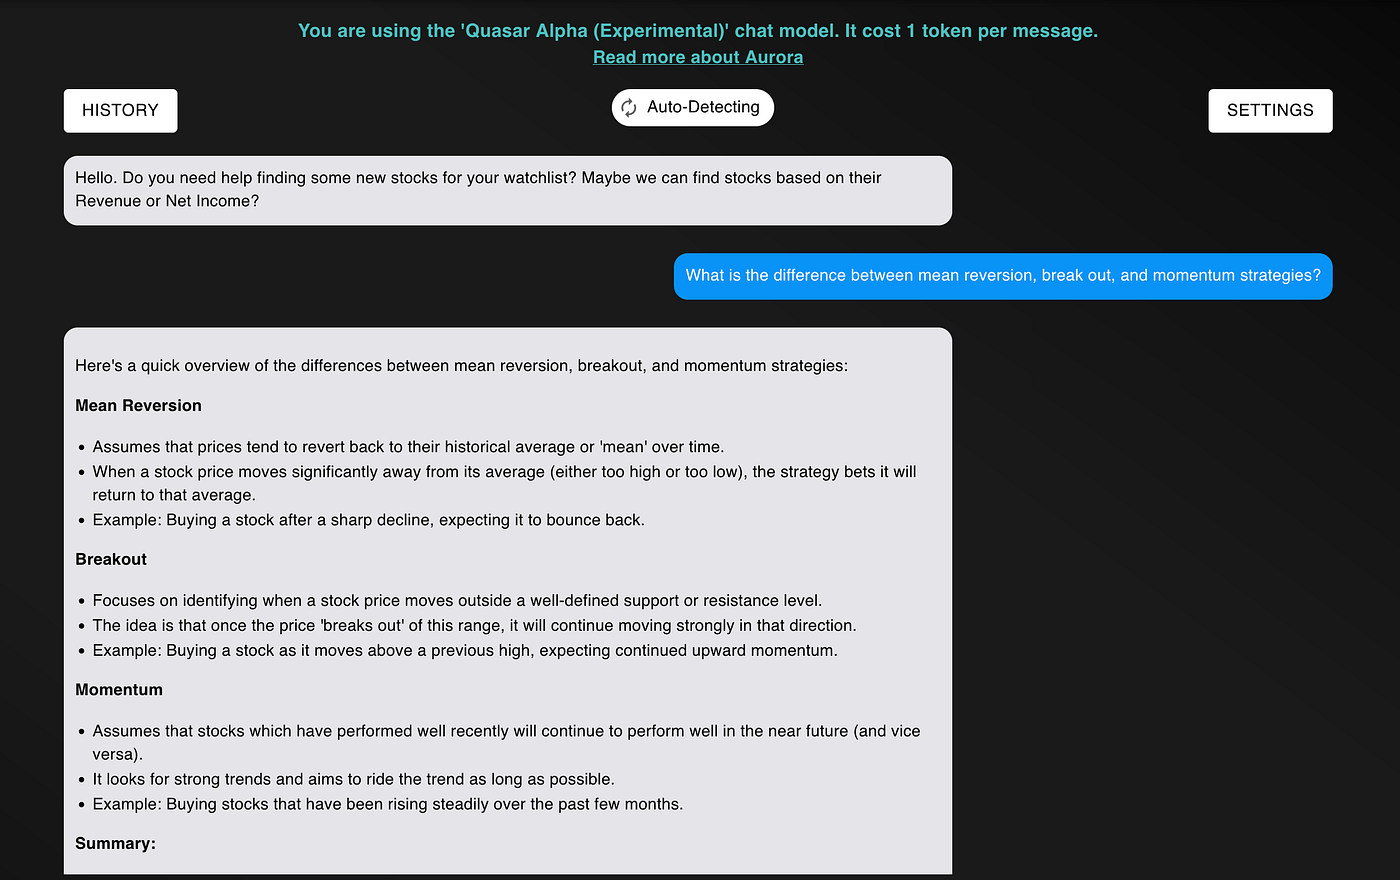
- I asked Claude questions about mean reversion, breakout, and momentum strategies
- I asked it to identify which indicators belong in each category
- I then used this knowledge to create a trading strategy
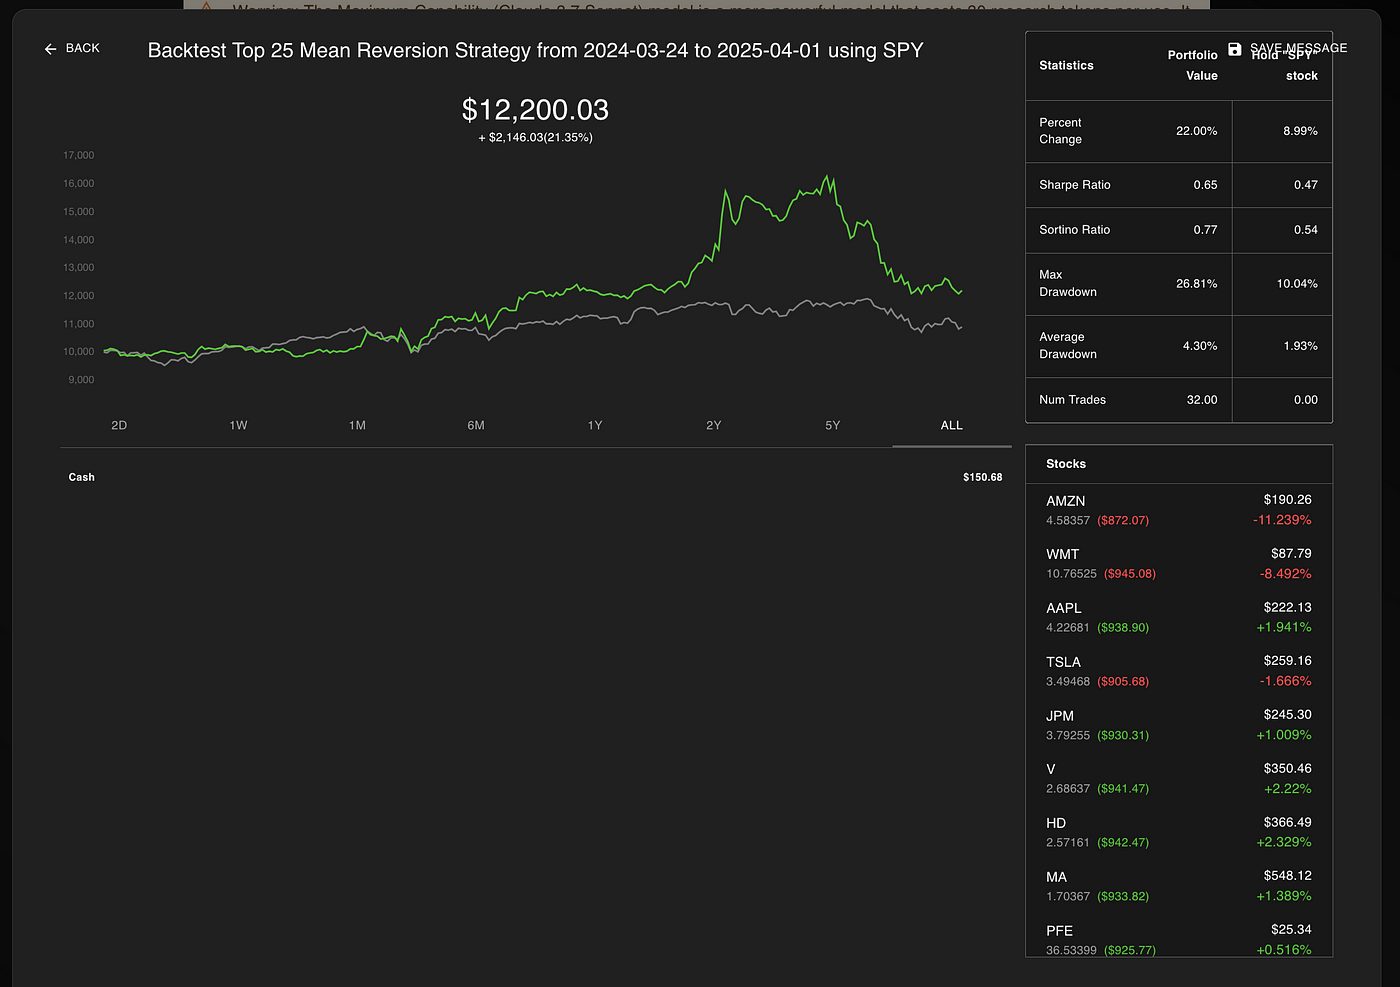
I then shared the portfolio publicly for anybody to audit or subscribe to.
Portfolio Quasar Alpha Prime — NexusTrade Public Portfolios
View and analyze trading strategy for portfolio Quadar Alpha Prime. See performance metrics and consider…
nexustrade.io
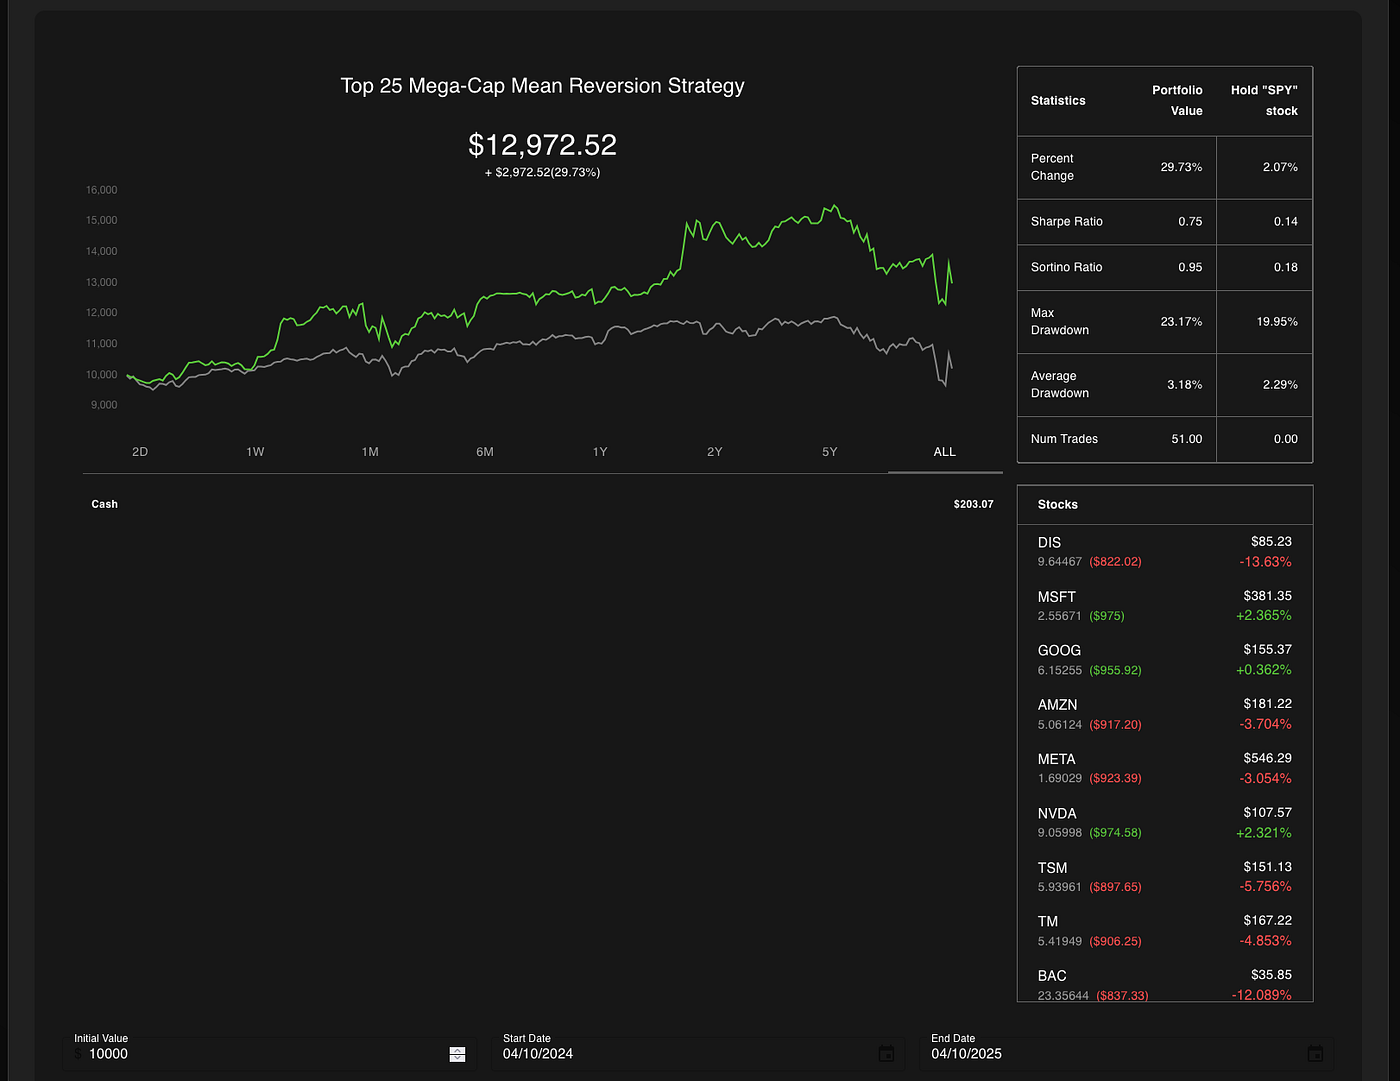
The main experiment below uses Quasar Alpha. The separately captioned Optimus Alpha run reports about 30% versus 2% for SPY from April 10, 2024 to April 10, 2025; the Quasar comparison later reports 29% versus 2%. Keep those two labelled runs separate.
Replicating the results with Quasar Alpha
When re-running this experiment with Quasar Alpha, I pretty much did the exact same thing that I did with Claude 3.7 Sonnet, down to using the exact same inputs.
For the full conversation, that you can copy to your NexusTrade account, click here.
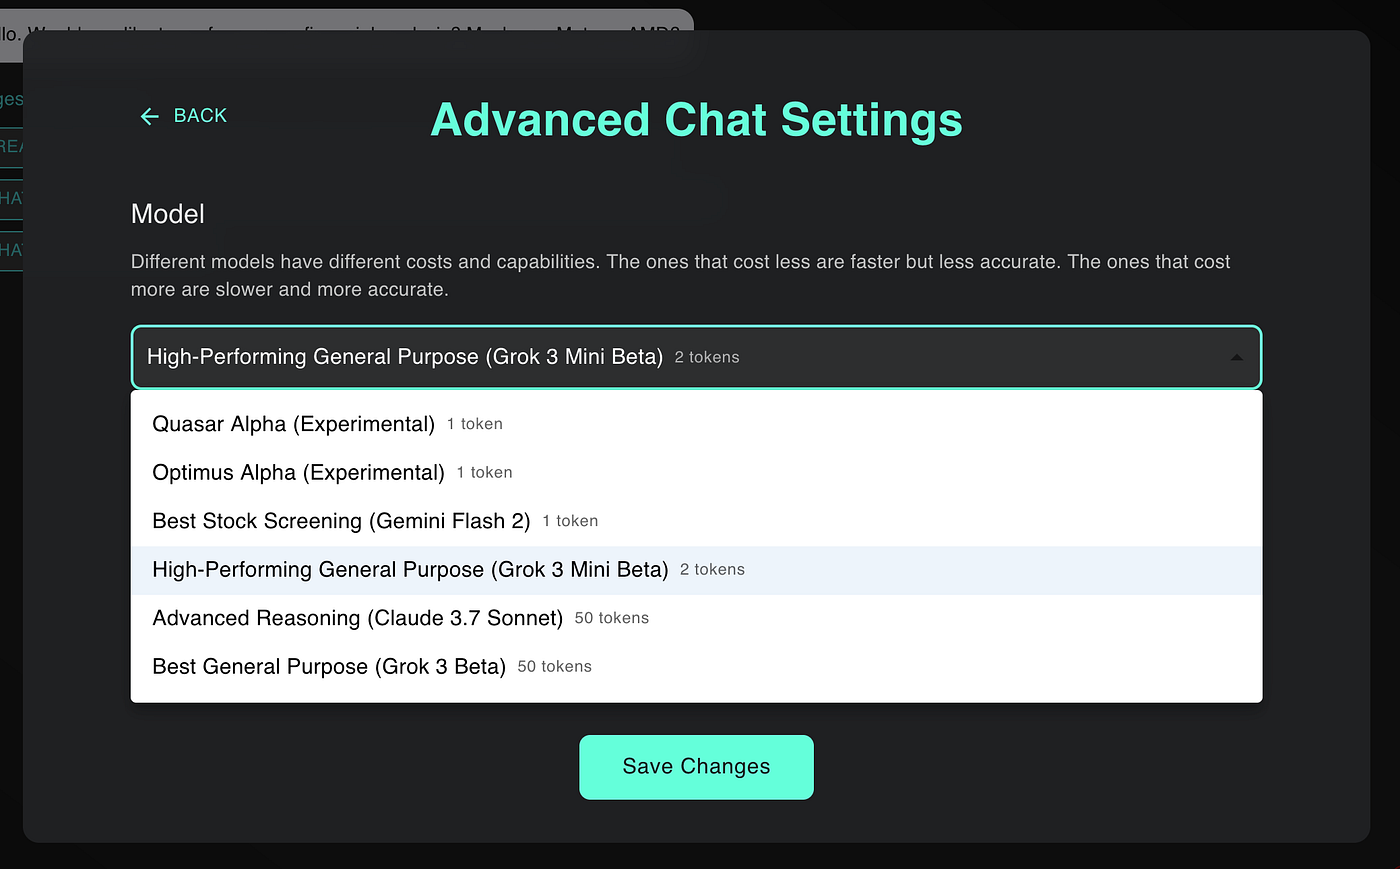
The only thing I changed was the model by clicking “Settings”.
I then questioned the model about its knowledge of mean reversion.
Then, like in the last article, I gave it a list of indicators and asked it to classify them as mean reversion, breakout, or momentum.
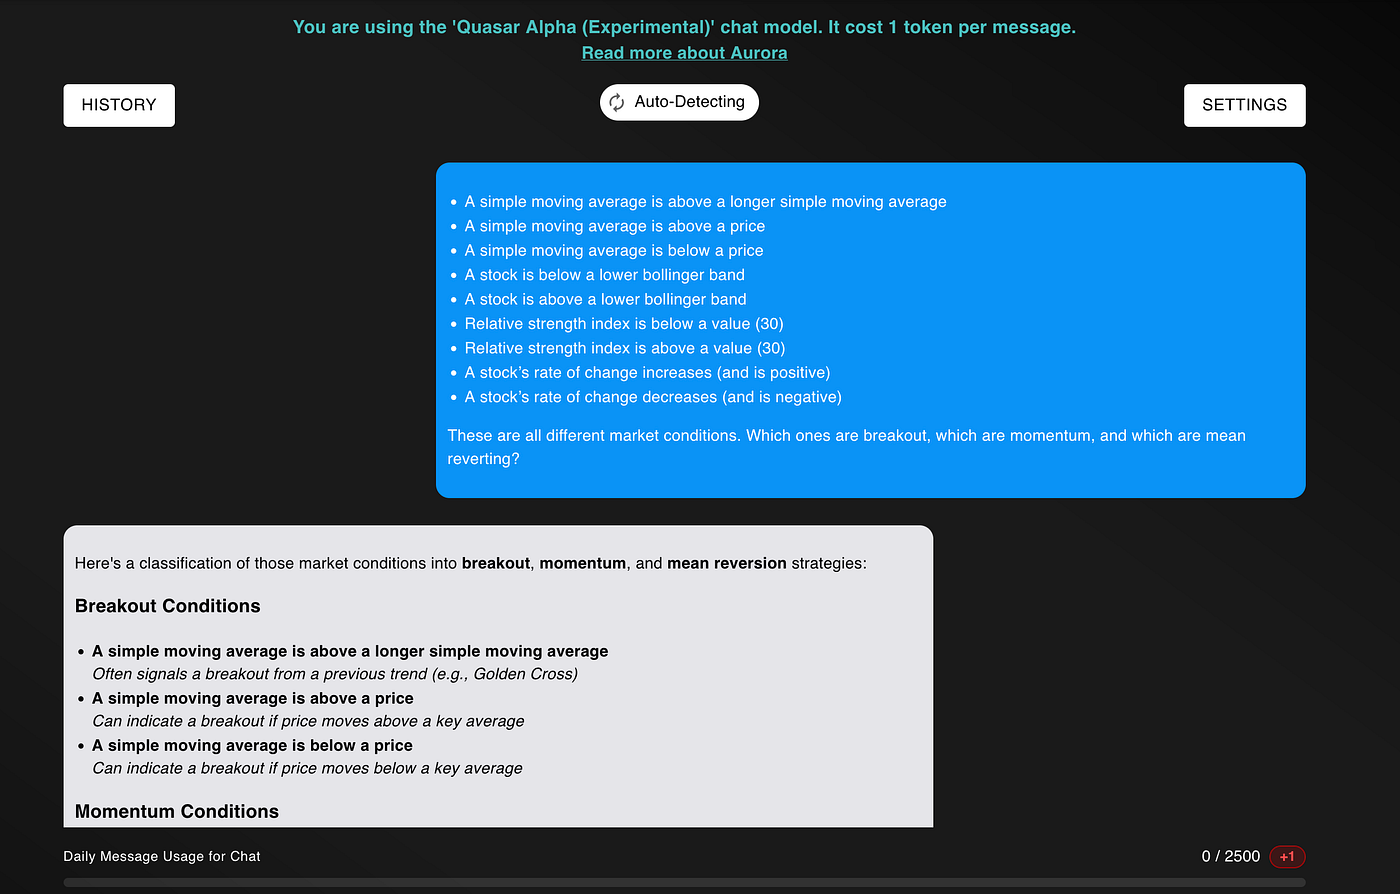
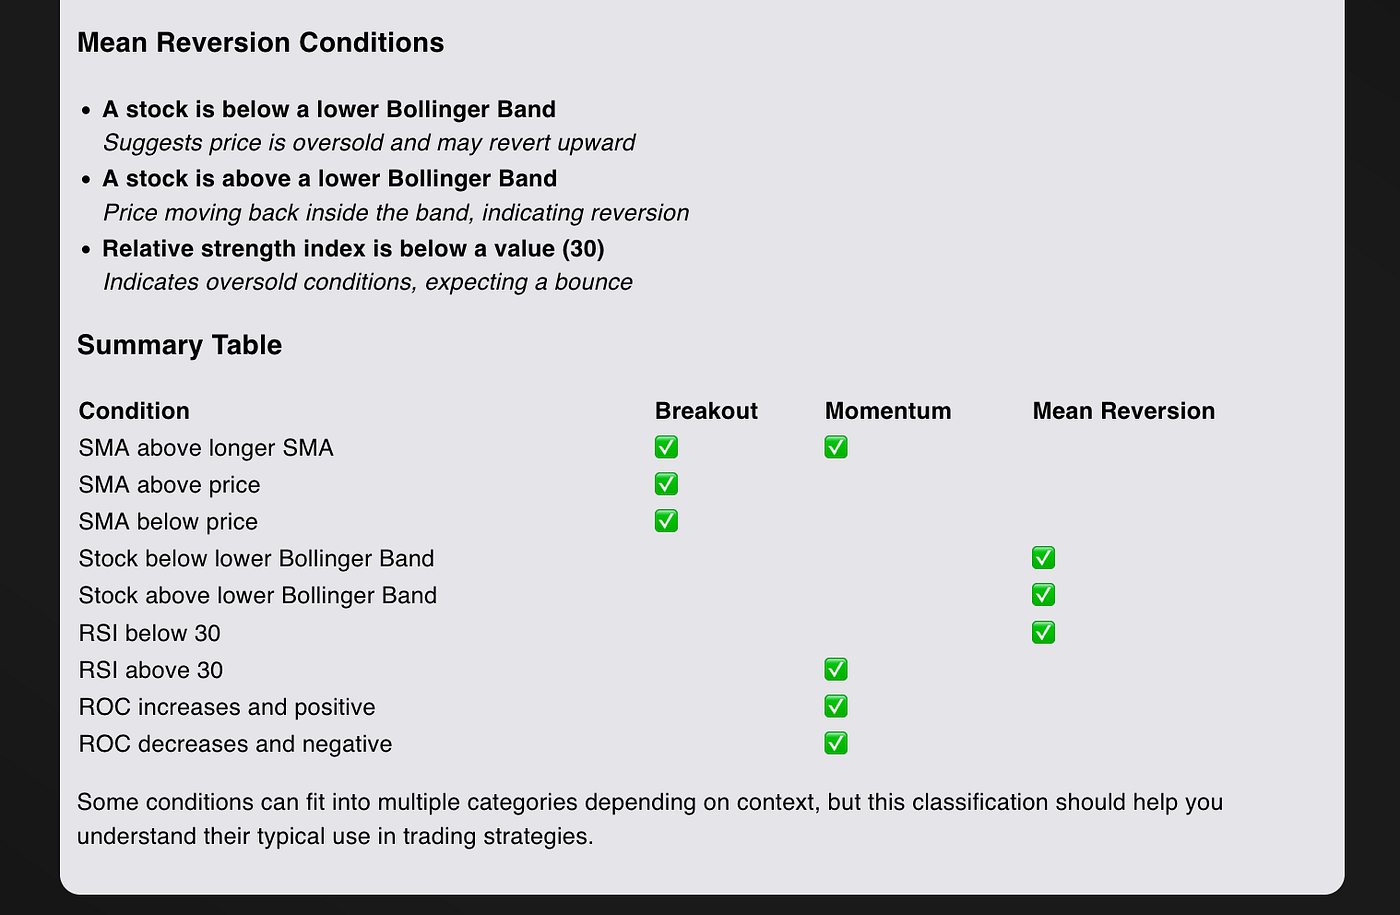
Unlike Claude 3.7 Sonnet, the answer given by Quasar was EXTREMELY thorough; like it truly understood the difference on a fundamentally different level.
It even included a markdown table that uses emojis to explain the difference like I was a complete beginner. I was floored!
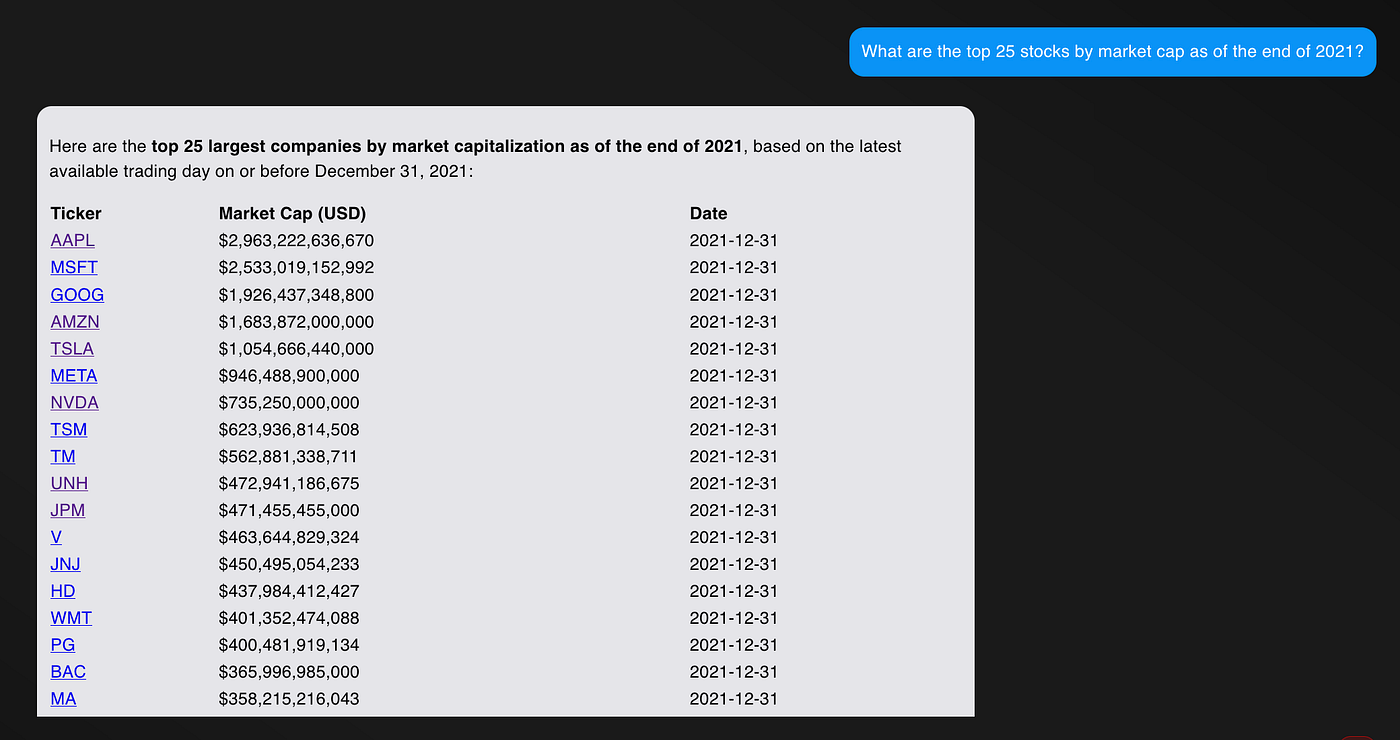
I fetched the top 25 stocks by market capitalization as of the end of 2021, then used that selected universe for the January to June 2020 COVID illustration. That uses later membership information: it is a retrospective conditional test, rather than an investable 2020 simulation with an as-of-2020 universe.
And finally, I created the trading strategy.
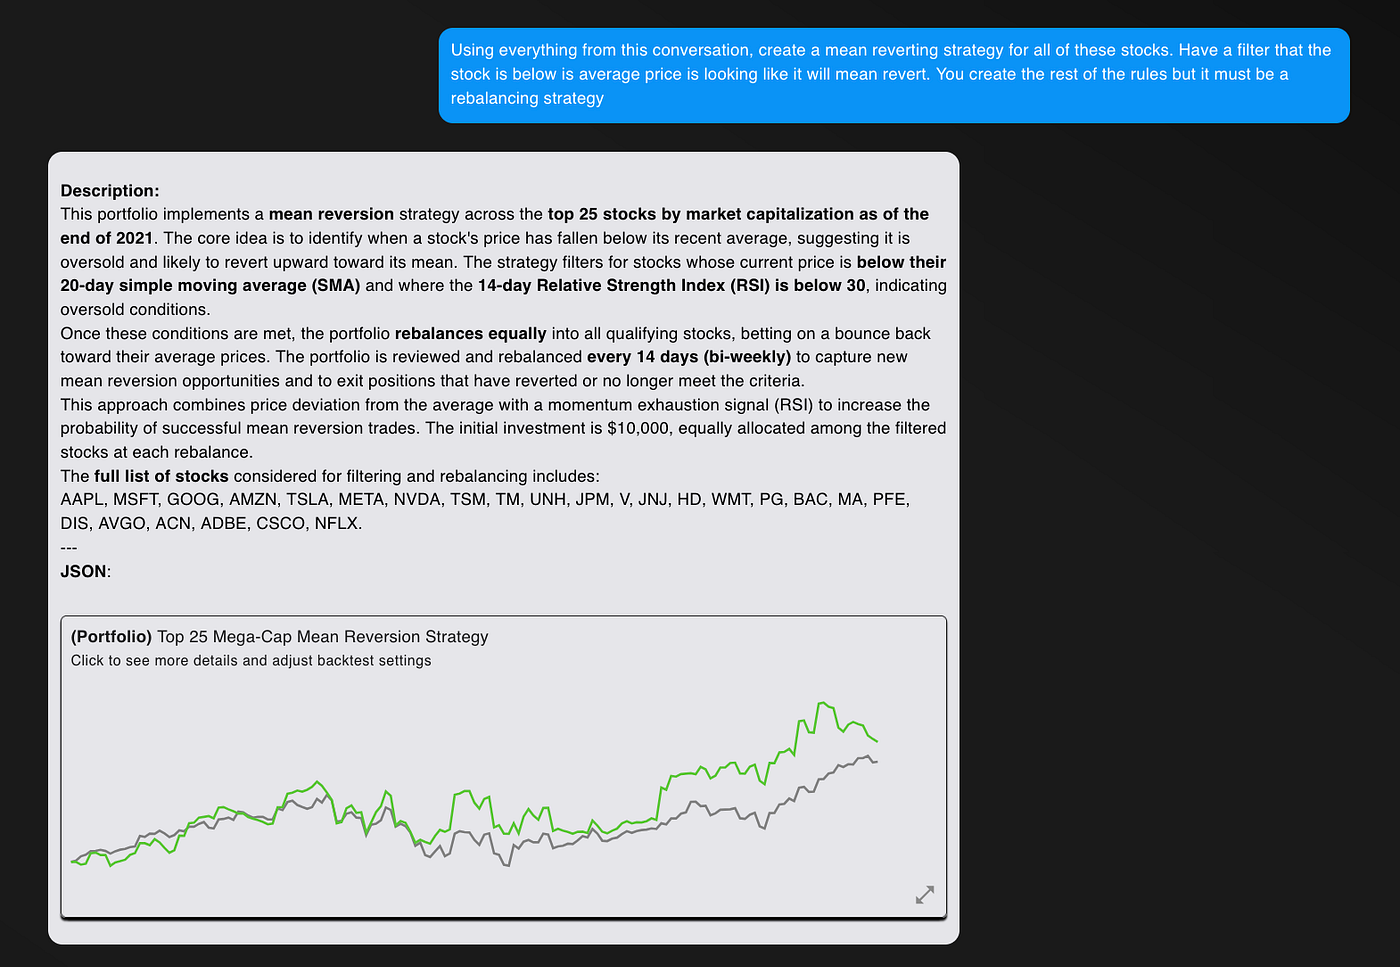
And, as you can see from the first backtest, the green line (the mean reverting strategy) is SIGNIFICANTLY outperforming the grey line by a very wide margin.
But it gets even crazier.
How good does the model get?
Let’s do the ultimate backtest for any trading strategy.
How good would it have performed in the past year?
The answer is “INSANELY good”.
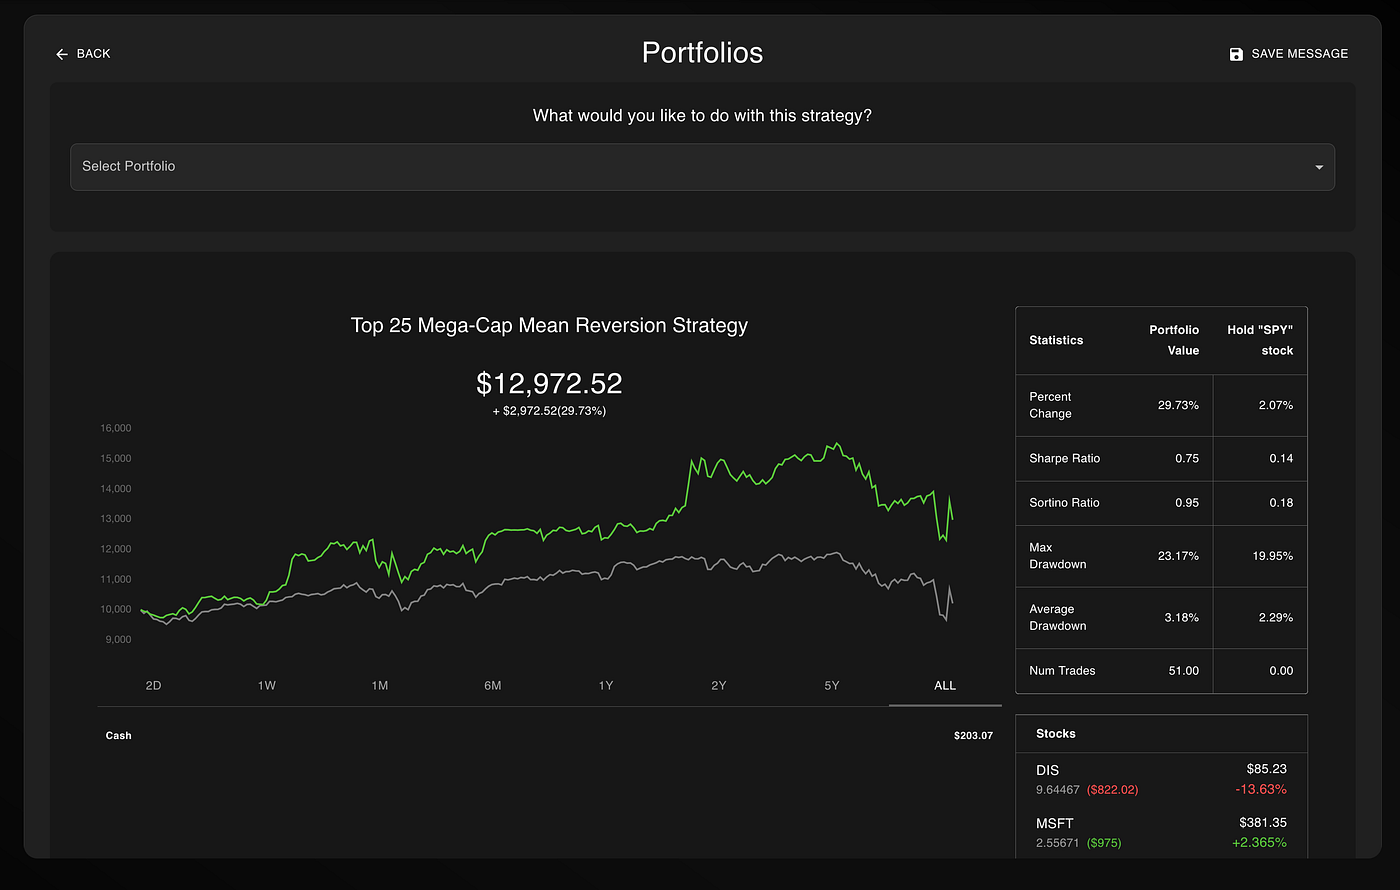
In the past year, this strategy gained 29%. In comparison, SPY gained two.
Yes, you read that correctly. SPY gained 2%.
Additionally:
- The strategy has a MUCH higher sharpe ratio (0.75) compared to SPY (0.14)
- It also has a much higher sortino ratio (0.95 vs 0.18).
- AND the drawdown is only slightly higher (23% versus 20%).
That means that if you were invested in the broader market this year, you essentially didn’t make any money. But if you had this strategy on autopilot, you would’ve had one of the best rallies of your life.
If we compare this to the Claude strategy, it outperformed the market only marginally.
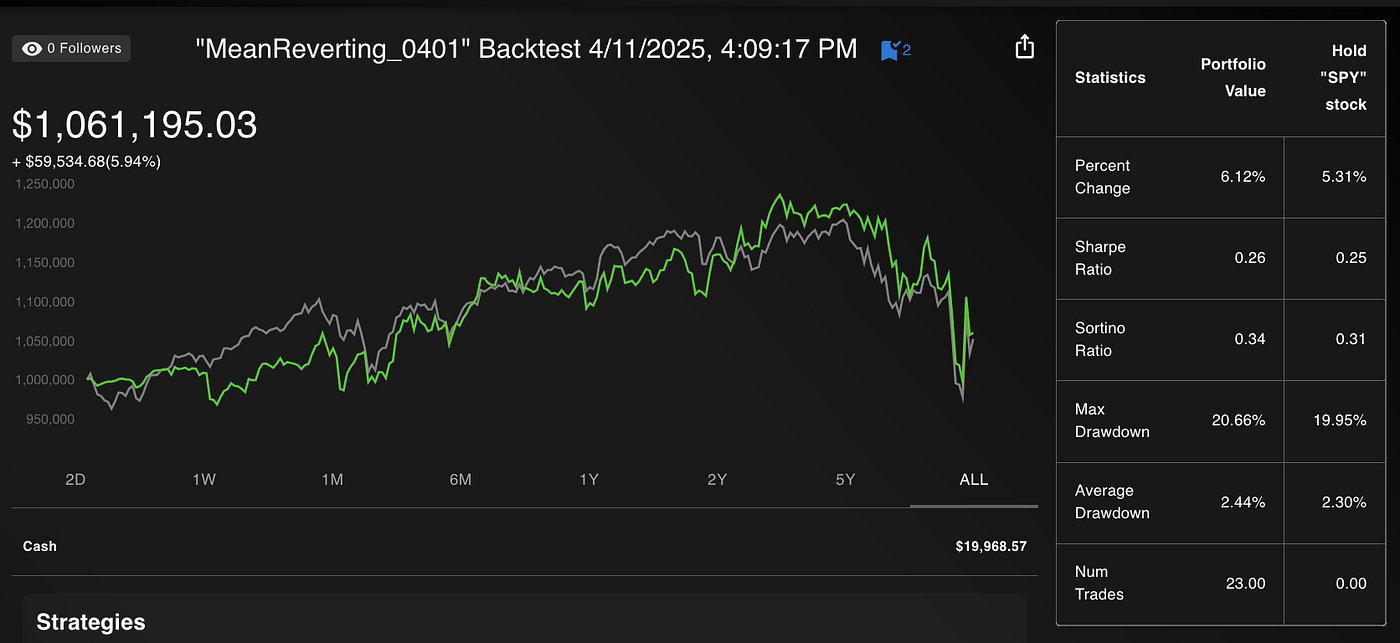
You can subscribe to it right now, and receive real-time notifications when a trade is executed. To do so, click here.
Portfolio Quasar Alpha Prime — NexusTrade Public Portfolios
View and analyze trading strategy for portfolio Quadar Alpha Prime. See performance metrics and consider…
nexustrade.io
Paired with an expert human trader, this strategy has the potential to completely change how we approach the stock market.
How bad does the strategy get?
While these results are absolutely incredible, they do NOT suggest we found the Holy Grail.
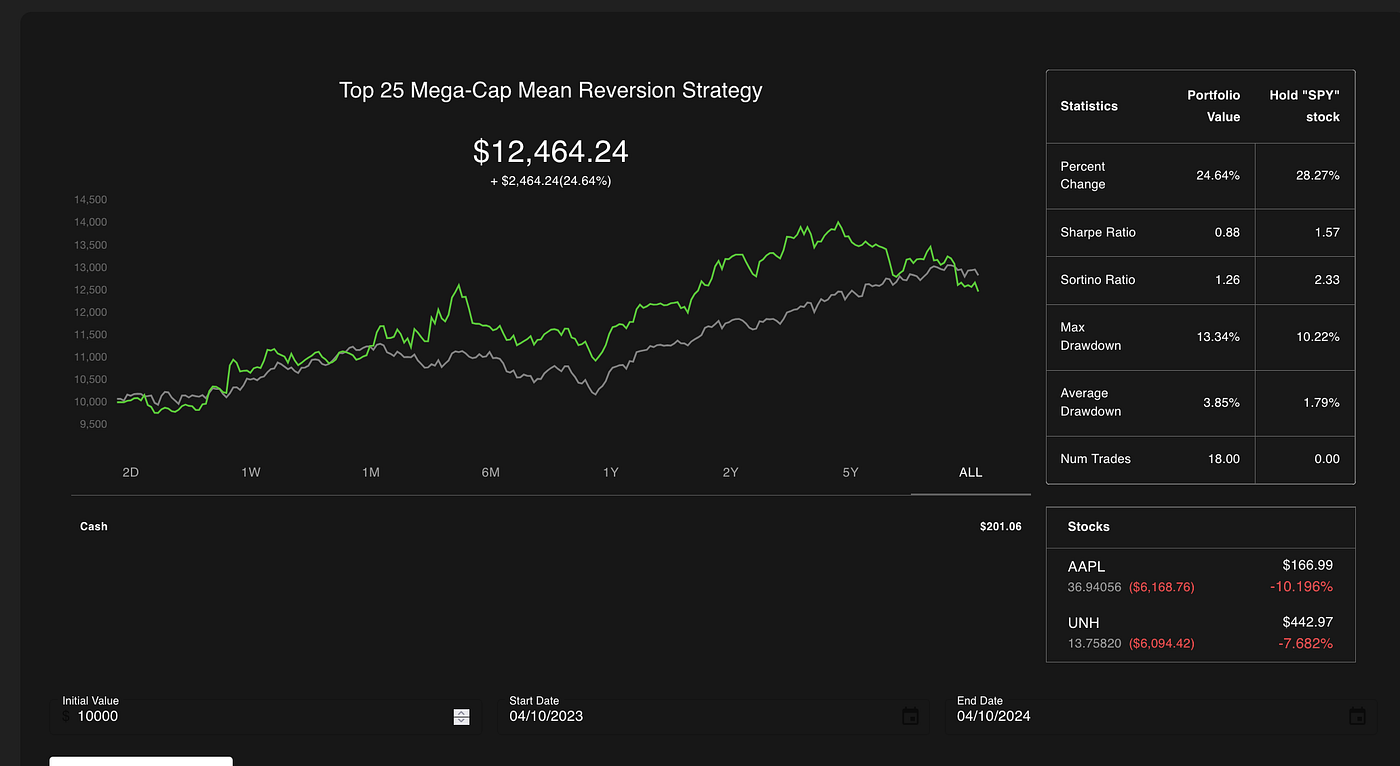
For instance, if we backtest it from 04/10/2023 to 04/10/2024, we see that it actually slightly underperforms versus the broader market.
Another example is a different period of unprecedented volaility. For if you backtest this strategy 01/01/2020 to 06/01/2020, you can see that it does far worse than the broader market.
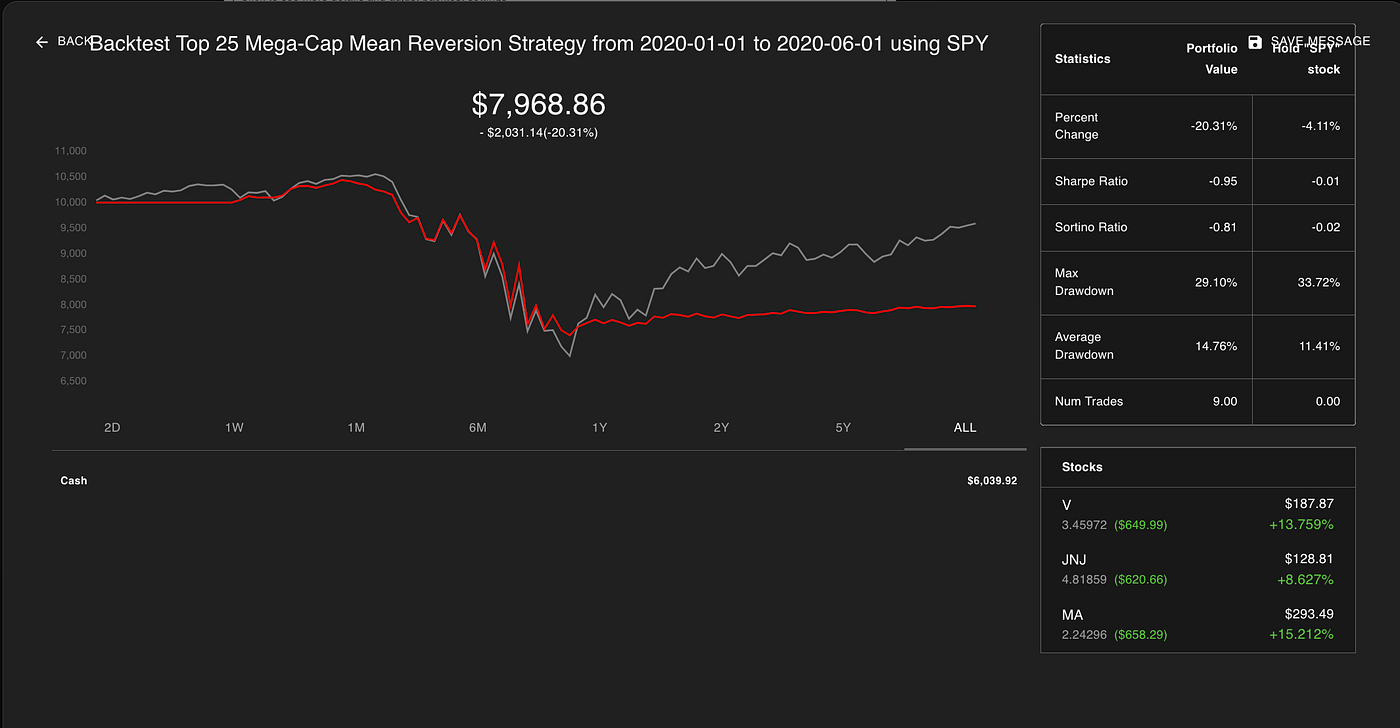
This was during the Covid pandemic which had unprecedented volatility. If you chose to have this strategy during that time, you would’ve lost over 20%, while the broader market eventually recovered and only lost 4.
Despite the fact that this strategy has done VERY well in recent years, there has been times in which the strategy did horrible. These periods show that this strategy is NOT a “Holy Grail”. It is one of many strategy that you can learn from and apply to your trading toolkit.
And, just like with the Claude-generated strategy, I’m going to deploy it publicly to the world and see how it holds up across the next year with paper-trading.
How does the strategy work?
The strategy works by rebalancing the top 25 stocks by market cap periodically whenever one of its conditions is true.
Specifically, this is the exact rule the algorithm uses.
Rebalance [(AAPL Stock, 1), (MSFT Stock, 1), (GOOG Stock, 1), (AMZN Stock, 1), (TSLA Stock, 1), (META Stock, 1), (NVDA Stock, 1), (TSM Stock, 1), (TM Stock, 1), (UNH Stock, 1), (JPM Stock, 1), (V Stock, 1), (JNJ Stock, 1), (HD Stock, 1), (WMT Stock, 1), (PG Stock, 1), (BAC Stock, 1), (MA Stock, 1), (PFE Stock, 1), (DIS Stock, 1), (AVGO Stock, 1), (ACN Stock, 1), (ADBE Stock, 1), (CSCO Stock, 1), (NFLX Stock, 1)]
Filter by ( Price < 20 Day SMA) and (14 Day RSI < 30)
Sort by 1 Descending
when (Greater Than Or Equal 1 of the conditions must be true:
((AAPL Price < 20 Day AAPL SMA)
and (14 Day AAPL RSI < 30)), ((MSFT Price < 20 Day MSFT SMA) and (14 Day MSFT RSI < 30)), ((GOOG Price < 20 Day GOOG SMA) and (14 Day GOOG RSI < 30)))
and ((# of Days Since the Last Filled Buy Order ≥ 14) or (# of Days Since the Last Filled Sell Order ≥ 14))
Breaking this down:
- We will rebalance the top 25 stocks that we fetched earlier at equal weights (all of the stocks are paired with the value “1”)
- We filter to only stocks who has a current price below its 20 day average price and whose RSI is less than 30
- At least one of AAPL, MSFT or GOOG must satisfy BOTH price below its 20-day SMA AND 14-day RSI below 30. Separately, the trigger requires either the buy-order day counter or the sell-order day counter to be at least 14. These are separate filled-order counters, not one last-rebalance timestamp.
Hypothetical trigger: MSFT below its 20-day SMA with RSI 28 satisfies the stock condition. A buy counter of 5 days and sell counter of 15 days satisfies the counter OR, so the combined trigger passes. If MSFT’s RSI were 35 and neither AAPL nor GOOG satisfied both tests, it would fail even with that sell counter. This explains the printed condition, not a recorded trade.
But, by doing so creates a textbook mean-reverting strategy, which do particularly well in volatile and sideways markets. With the controversies around Trump issuing tariffs, this strategy might be better off than just blinding holding an index fund.
Finally, due to the transparent nature of the NexusTrade platform, anybody can whip up a Python script and re-create the rules for themselves. This isn’t an AI with a secret black box inaccessible to everybody. The rules are literally available to you right now if you’re paying attention.
How you can use models like Quasar Alpha to create your own market-beating strategies?
The awesome thing about this is that the methodology is not being gate-kept. You can try it yourself right now for 100% free.
To do so:
- Go to NexusTrade and create a free account
- Go to the AI chat page
- Literally just type what I typed (or create your own ideas and share them with the world)
The NexusTrade platform is as transparent as possible. You can audit the decision-making, see the exact trading rules, and even peek at the underlying JSON behind the strategies to make sure everything makes sense.
You don’t have to create your own trading platform to use AI to improve your decisions. You just have to create a trading strategy.
Implications of these results
The implications of this are quite literally mind-blowing for anybody who’s been paying attention. Using NexusTrade, you can quite literally click this a button and subscribe to a portfolio that was created fully using AI.
Portfolio Quasar Alpha Prime - NexusTrade Public Portfolios
View and analyze trading strategy for portfolio Quadar Alpha Prime. See performance metrics and consider…
nexustrade.io
With AI being 100% fully capable of creating portfolios, imagine the future of what they can do with managing them.
This doesn’t even touch upon the fact that we can run simple algorithms like genetic optimization to find the most optimal hyperparameters.
This is, in theory, the BEST mean-reverting strategy. Here’s how I created it in less than 3 hours.
How retail investors are using an algorithm inspired by evolution to beat Wall Street.
ai.plainenglish.io
Models like Quasar Alpha prove that the AI race isn’t slowing down at all. In fact, it’s going faster; AI is everywhere and its not going away. And one day, it might be used to manage your retirement portfolio.
But not today.
Important Risk Disclaimer
The Obligatory Risk Warning: Just so I’m crystal clear about something — this strategy isn’t a guaranteed money printer. Especially in 2025, this market is WILD and nearly unpredictable. What works beautifully today might completely fall apart tomorrow. We’ve seen this strategy struggle during COVID and underperform in certain periods. Past performance is NOT a promise of future results. You absolutely should not throw your life savings into this without understanding you could lose a chunk of it.
The backtests don’t show the full story: The charts look pretty and exciting, but they are only a snapshot of time. Real-world trading comes with slippage, fees, and execution delays that can eat into those beautiful returns. Markets evolve — and strategies that worked yesterday can suddenly stop working. Even the best AI can’t predict every market curveball (especially when thrown by President Trump). This is why no strategy, no matter how brilliant, replaces human judgment and risk management.
Concluding Thoughts
The Quasar Alpha experiment reports 29% versus SPY’s 2% in its later one-year comparison, with Sharpe 0.75 versus 0.14, Sortino 0.95 versus 0.18, and drawdown 23% versus 20%. The separately labelled Optimus result is not this run. Both are historical simulations; the hidden provider/model identity remained unconfirmed in this April 2025 account.
While these results don’t guarantee future performance, they highlight how quickly AI is transforming investment strategies. What was once the domain of elite quant firms with teams of PhDs is now accessible to anyone with an internet connection.
NexusTrade has made this power available to everyone. You don’t need coding skills, financial expertise, or even trading experience. The platform’s transparency lets you audit every decision, examine the trading rules, and verify the underlying mechanics.
Ready to harness the power of AI for your investments? Visit NexusTrade today to create your free account.
NexusTrade - No-Code Automated Trading and Research
Perform financial research and deploy algorithmic trading strategies
nexustrade.io
You can use the exact prompts from this article, develop your own ideas, or simply subscribe to the Quasar Alpha Prime portfolio with a single click. Get real-time notifications when trades execute and stay ahead of the market with AI-powered strategies that anyone can use.
Don’t get left behind in the AI revolution. Join NexusTrade now and discover what the future of trading looks like. It’s here, right now.
Don’t miss it.
No comments yet.